We’re a little tight on cash. How can we shift some settlement costs to reduce out of pocket expenses?

Some buyers reduce the cash needed at settlement by scheduling closing at the end of the month. But there are several other ways to save on closing costs that may work better in the long run.
Skip late-month settlement

Since interest on the loan is paid to the end of the month at settlement, the interest payment gets lower as you get closer to the end of the month. But another approach is to wait a few days until the beginning of the next month. That way, you'll need to pay more up front at settlement, but you'll gain a whole month's delay before the first full mortgage payment is due, because mortgage interest is paid in arrears, after the month has passed.

Reduce out-of-pocket cash

Another way to reduce the cash needed at settlement takes some advance planning. By negotiating with the seller, the buyer may be able to pay more for the home and finance it, while the seller puts an equal amount toward out-of-pocket settlement costs.

Finance closing costs

A third option is to find a lender who will finance closing costs by wrapping them into the mortgage. This method may, however, cost more over the long run, as lenders often will then charge a higher interest rate for a "no closing costs" loan.

Seven Ways to Save for Your Down Payment

Very few things in life are quite as exciting as buying your first home. It's part of the American dream. And although home prices keep rising, ownership is within the realm of possibility, even for those who don't make humongous salaries. Of course, the larger your down payment, the lower your monthly payments. And if you can come up with 20 percent, you avoid paying expensive private mortgage insurance (PMI).

Why you want to avoid paying PMI: PMI typically costs about 1/2 of 1 percent of the loan. For example, if you put down 10 percent on a $100,000 house ($10,000), your annual PMI costs will be $450. And, these payments are not tax deductible. If your down payment is less than 20 percent of the sale price, you must take out PMI.

Here are seven ways to begin on your mission of ownership...

Step one: Get with the program

The first step toward saving enough money for a down payment is a psychological one—desire. You (and your spouse or friend) must REALLY want to buy a house. With enough passion for ownership, you'll find yourself motivated to save every penny you can.

To boost your desire, spend a weekend looking at houses or condos within what you think is your price range. Saving will be a whole lot easier if you have a vision of a two-bedroom, two-bath house with white shutters on Elm Street dancing in your head. This vision will make it easier to say no to shopping sprees, buying a second car or going on an expensive vacation.

Take pictures of your favorite properties and tape them to your refrigerator door or better yet, prop them up on your desk next to your checkbook.

Step two: Review your budget

Or, if you're budget-free, draw one up. Get help making a budget
here. Then list those areas where you can cut back on spending and earmark that money for your special Down Payment Account (DPA). Don't cut out everything that's fun ... you want to enjoy life BH (Before the House), but do start to be more cautious.

Here are some savings tips to get you in the right frame of mind. Add your own to the list.

· Drive at the speed limit. Traveling at 65 mph versus 55 mph increases fuel consumption by a whopping 20 percent. (GM Motor Club)
· Clip coupons. If you save $25 a month with food and drug coupons, that turns into $360 a year.
· Take your lunch to work. If you're spending $8 a day on a sandwich, Coke and an ice-cream cone, that's $2,000 a year, assuming two weeks out for vacation. And that's not counting those in-between snacks of chips, pretzels and cappuccino. Figure out what you spend per day on lunch; then on the days you brown bag it, put that amount into your DPA.
· Carpool. Or, walk, bike or take the bus to work. Taxis are a guaranteed way to spend $5 in five minutes.
· Talk less. Make sure you have the cheapest calling plan. And if you make a lot of long distance calls, get a prepaid phone card.
· Skip the babysitter. Set up a co-op arrangement with friends and neighbors.
· Stop smoking. Quitting a pack-a-day habit will save you about $1,095 a year.
· Cut back on dining out. Send the amount you save to your DPA.
· Never open a catalog. Toss them out immediately. If you peek inside you're bound to find something you like.
· Don't carry much cash. If you leave your ATM card, your credit card, your debit card, your checkbook, and most of your cash at home, it will be hard to spend much. Instead, carry enough cash for the day plus one bank check and for emergencies, several traveler's checks.

Step three: Open a DPA

You'll need a special account to hold your savings, such as a high-yielding bank savings account or certificate of deposit (CD).

Keep in mind that bank CDs have a definite advantage over a money market or savings account: The money in a CD is tied up until it comes due. In other words, you'll be penalized if you take the money and run before the maturity date. Bottom line: You'll be less apt to use this money for something other than your house. CDs come in a variety of maturities from one to five years. Figure which time horizon matches your ownership goal.

$Tip: Be sure to read Certificates of Deposit: Tips for Investors, a free SEC publication. Find it
here.

Step four: Tell your family

If your parents or other relatives send you presents for your birthday, anniversary or the holidays, they might instead contribute to your DPA. Don't insist—some parents prefer to shop for special gifts for their kids. However, it won't hurt to let them know about your goal.

Step five: Go automatic

If you don't see it, you won't spend it. Arrange for a certain dollar amount to be taken out of each paycheck and automatically transferred to your savings or money market account at your bank or credit union. If you're self-employed, set up the same type of plan at your bank and have money transferred each month from checking to savings or to a mutual fund.

Step six: Reduce credit card debt

Always pay at least the minimum due each month on your cards to avoid high interest rates. Better still: Pay each bill in full and completely avoid high rates on unpaid balances. And make certain you mail the check (or transfer the money) well in advance of the payment date. A growing number of credit card issuers are hitting customers with late arrival penalties.

$TIP: Ideally, you should wipe out credit card debt as quickly as possible. Begin by paying down the credit card with the highest interest rate first.

Step seven: Keep on a-paying

When you pay off a car loan or education loan or get rid of a credit card debt, continue to write a check for that same amount every month—but put it into savings. You've learned to live without that money, so now you can sock it away.

Lonnie Snyder
REALTOR®
Keller Williams Realty Southeast Sound
Phone: 206-406-2710
E-Mail : snyder@kw.com
Website: http://www.callsnyder.com/
Blogsite: http://renton-real-estate.blogspot.com/

Lonnie Snyder is a full time real estate agent and REALTOR® with Keller Williams Realty specializing in Residential Real Estate for buyers and sellers in Washington’s Kent, Renton, Newcastle and South Bellevue.
Power Outage Tips


Yep, It is getting that time of year again. Whether the culprit is the weather or an energy shortage, power outages can be a nuisance. Here are a few tips to help you get through:
Keep food cold by keeping the refrigerator door closed; place highly perishable items in a cooler with block ice or freezer packs.
Keep a supply of bottled water and some canned, non-perishable food on hand.
Make sure you have a flashlight and extra batteries in your home. I love the new EverLife flashlights that you just have to shake a little for them to work. A battery-powered radio will help you keep track of any storms.
Your cordless phone won't work during an outage, so be sure to have at least one conventional phone in your home in case of emergency.

Secret Tests To Check A Property’s Condition

If you’re considering buying a house that’s more than a few years old, there may be some hidden problems you can discover before you make a purchase offer. Although putting a professional inspection contingency in the contract will help protect you from surprises, doing your own inspection before making an offer could save you considerable time and money.
How can you tell if a property is worth buying? Here's how to look at the big picture -- for structural concerns, major repairs that are needed, appliances that have to be replaced.
Crawl The Walls
Start going to the right when you enter the house, and keep on following to the right. You will check each wall that way. Do the same on every floor. Look for settlement cracks, separating joints, defective plaster or other signs of stress or damage. Check wallpapered areas for crinkling or gathering, which may mean walls are settling or shifting.
Look For Leaks
Loose or wrinkled wallpaper could indicate a water leak somewhere. Look for water stains on the ceiling and walls. You may have to look closely -- bring a flashlight -- in case they have been painted over or repaired.
Spend time in the bathrooms and in every area with pipes, checking for leaks and drips. Also, run the shower and basin, then flush the toilet to check water pressure. Look for cracked or loose tiles and missing grout or mildew stains on the walls or floor, which could indicate a behind-the-wall leak.
Plug Into The Electrical System
Check every electric socket or outlet. Use a plug-in night light and turn every switch on and off. Look for extension cords and multiple plugs in sockets, which could mean insufficient or poorly placed sockets. Also check every appliance to be sure it works well.
Focus On Condition
Open and close every door and window. Look and listen for squeaking, sticking, or a tendency to close on their own. Check for evidence of shifting or settling around the front stoop, chimney and walks, and places where the driveway and the fence meet the house. Also check the deck for sturdiness and look for rotted wood. Go into the garage and check the walls, floors and doors -- inside and out.
Pay Attention To Pests
Look for termites and ants. Especially look along the foundation, around doors and entry points of wiring and pipes. Check the grading of the yard to be sure water runs away from the house.


If everything looks good to you and you decide to purchase the house, be sure to require a home inspection by a professional inspector before settlement. You will want a professional who will crawl into the crawl space, climb onto the roof and poke around with a flashlight in the attic. Your professional should also carefully inspect the major systems -- electrical, gas, plumbing and heating/air conditioning.
You can and should insist on a written report detailing what the problems are with the house, how important each one is. You may have to consult a contractor to estimate repair costs on any problems found.

Pitfalls of kitchen remodeling revealed

New book helps overcome obstacles

By Robert J. Bruss
Inman News

If you are thinking about renovating your kitchen, first read "Tips and Traps for Remodeling Your Kitchen" by R. Dodge Woodson. Especially if you are thinking of doing the work yourself or being your own contractor and hiring sub-contractors, this book will bring you to your senses.
Woodson, a contractor for more than 30 years, shares his expert insights into the kitchen remodeling business and all the important aspects. Placing a very high emphasis on price, the author explains the pros and cons of being your own renovation contractor or doing some of the work yourself.

If the book has a fault, it is Woodson makes some of the work seem too easy. For example, he makes "hanging Sheetrock" appear to be a simple job. It's not. Having been involved with many house and kitchen remodels on my properties, I've watched expert drywall workers; even these professionals sometimes have difficulties getting it right.
Although the book has many photos of remodeled kitchens, illustrating the topics such as floors and cabinets, it is mostly about hiring a general contractor or doing the work yourself. Woodson explains, often in painful detail revealing possible complications, what is involved in tearing out an old kitchen and replacing it with an up-to-date kitchen.
Not only does the author explain unanticipated problems that he has encountered over his 30 years of construction experience, but he emphasizes the possible pitfalls to be anticipated. If ever there was a book of required reading for kitchen remodelers, this is it because it exposes the pitfalls and how to overcome them.
Having watched many friends remodel their kitchens, I understand the possible problems. One couple I know took almost a year to complete their kitchen because the remodeling contractor they hired was a real dunce. After they fired him, they discovered other remodeling contractors didn't want to complete their project started by another contractor.
Woodson explains how to successfully remodel your kitchen. He begins with the basics, such as roughly drawing what you want and then interviewing several remodeling contractors. He emphasizes how to compare bids, check references, and then hire a contractor. Or, you can do it yourself based on the great information in this new book.
More important, the author emphasizes how to save money. He shares his calendar of when is the best time of year to hire a remodeling contractor. Don't tell, but the best time is November, December or January when most remodeling contractors are least busy.
In addition, Woodson explains how to get even a better price by agreeing with the contractor to make your remodel a "fill-in job" or a "reference job." A fill-in job is highly discounted because the contractor can work on it when his other jobs are tied up with sub-contractors who are late or he has time between jobs.
A "reference job" means the contractor can refer other prospects to inspect the work in your home. The author recommends becoming a "reference job" in return for a big discount. He says you are likely to get the highest quality work and best service because the contractor will be using you as a reference.
Any homeowner considering remodeling his/her kitchen must read this book for its "insider information," which only an experienced remodeling contractor knows. To illustrate, Woodson explains why homeowners can save by shopping for materials among suppliers to get the best discount prices. He even shares how homeowners can get the customary contractor's 10 percent discounts.
Chapter topics include "Planning Your Job"; "Drawing Your Own Rough Plans"; "Solidifying Plans and Estimating Job Costs"; "Choosing Your Materials"; "Getting Your Best Price on Materials"; "Subcontractors"; "Selecting Contractors and Subcontractors"; "Dealing with Contractors"; "Code Considerations"; "Financing Your Project"; "Ripping Out Kitchens"; "Unexpected Conditions"; "Flooring"; "Walls and Ceilings"; "Mechanical Work"; and "Cabinets, Countertops, Fixtures, Trim and Appliances."
This ultra-complete guidebook for kitchen remodelers cannot be recommended too highly. It won't help you decide what kind of kitchen you want. But it will show you how to profitably deal with the contractors and sub-contractors. On my scale of one to 10, this simple book scores an off-the-chart 12.
"Tips and Traps for Remodeling Your Kitchen," by R. Dodge Woodson (McGraw-Hill, New York), 2005, $16.95, 202 pages; Available in stock or by special order at local bookstores, public libraries, and www.amazon.com.

Blast From The Past

PastLove that retro look? You're not alone. Vintage and retro home furnishings, housewares and collectibles are hot.
If you're looking for authentic Fifties fabrics, a retro chrome floor lamp or starburst clock, or you just want to take a trip down memory lane, you may find these websites worth checking out:

Townhome Just Listed in Renton

SOLD

I have more Homes avebale.

Please call me.

(206) 406-2710

.

19166 110th Pl SE Renton 98055
See Additional Pictures
Status Active Listing# 25135859 King County
Beds 2
Baths2.50
Gas Fireplace 1
List Price 224,750

Year Built 1998 Townhouse

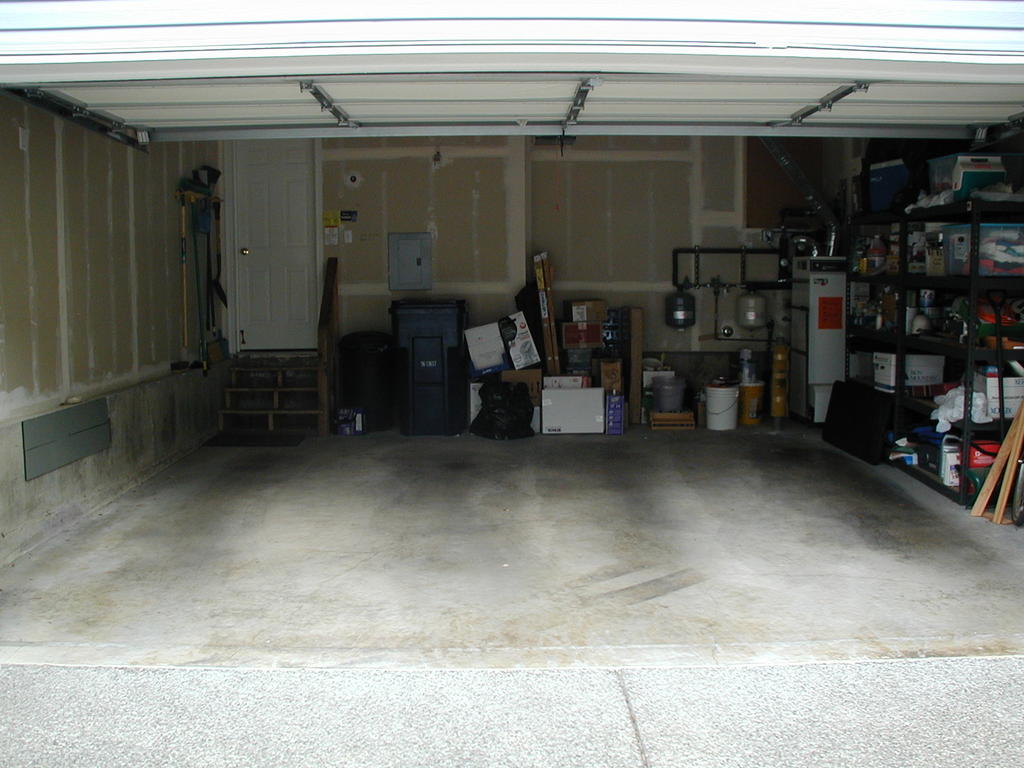
Covd Prkg. 2 Garage-Attached
SQFT 1194
Map: 686 Grid: D-2
Appliances
Dishwasher, Dryer, Garbage Disposal, Range/Oven, Refrigerator, Washer

Interior Features : Bath Off Master, Ceiling Fan(s), Dining Room, Dble Pane/Strm Windw, Pantry, Security System, Vaulted Ceilings, Walk-in Closet


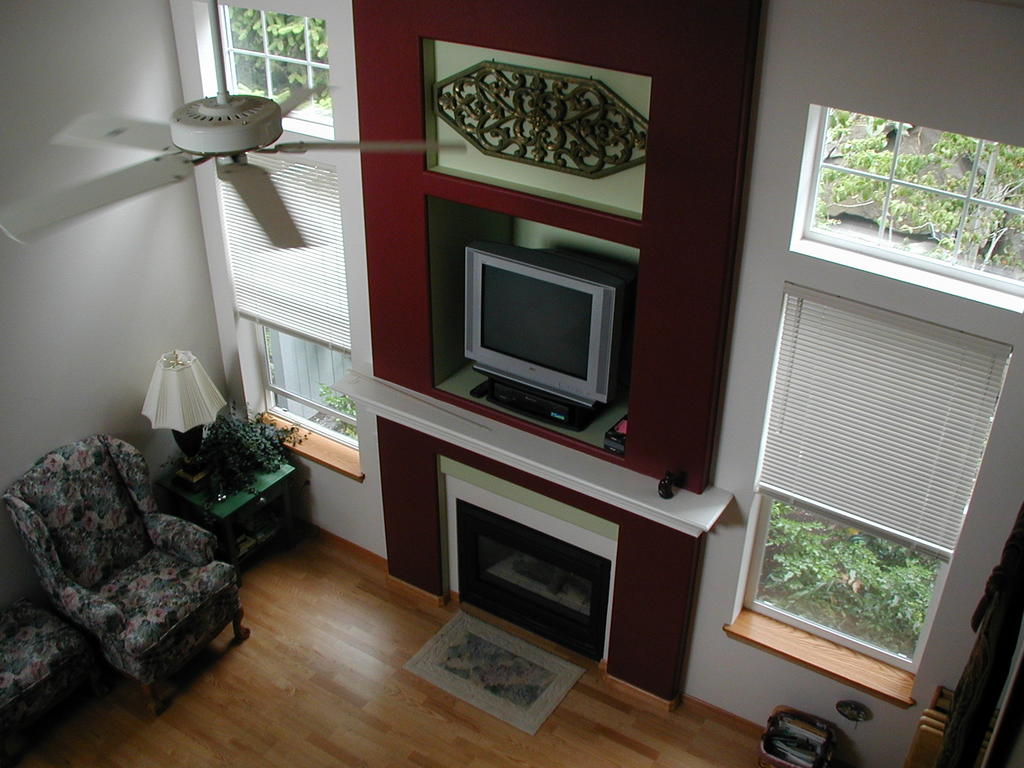
Location, Location. This wonderful town home has new red oak floors on the main level. The livingroom has vaulted ceiling and lots of tall windows. The diningroom has a glass sliding door to take advantage of the private back yard. Large kitchen with ample cabinets & counter space. This freshly painted home has a master bedroom with a large walk-in closet and a full bath. Also 2nd bedroom has it's own private bath. A 2 car garage,gas fireplace, powder room & much more. Come see it before it is too late.

Please Call me for more info.

(206) 406-2710

Lonnie Snyder / Keller Williams SE Sound
Lot Sizes And Square Footage Are Estimates.
Information From Reliable Sources, But Not Guaranteed.